
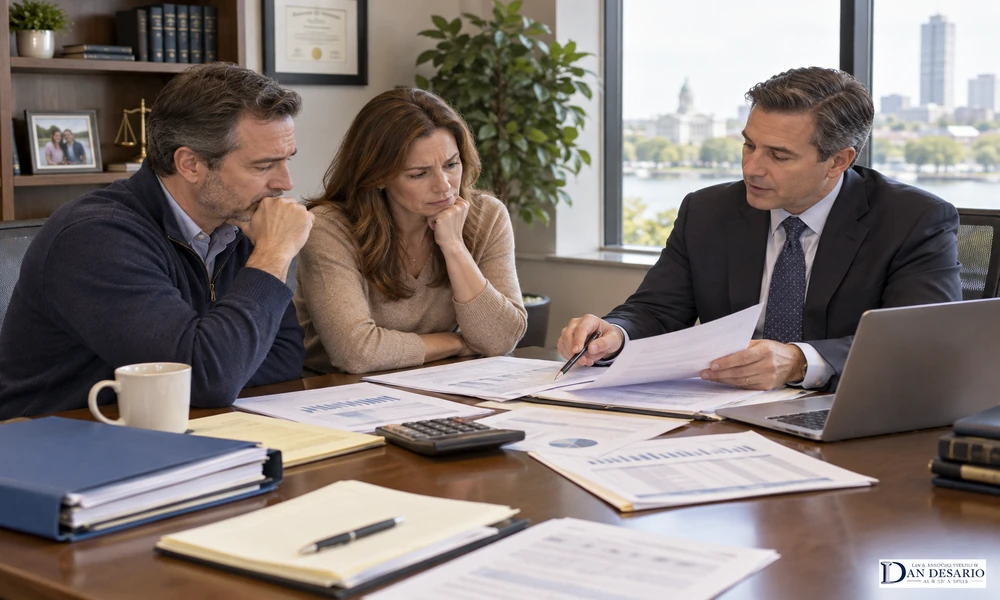
Divorce can turn everyday financial decisions into long-term consequences. Spouses may be focused on reaching an agreement or simply getting through a difficult transition, but overlooking debts, accounts, taxes, or property values can create problems well after the divorce is finalized. Understanding the financial picture before making major decisions can help prevent avoidable mistakes.
Failing to Understand the Full Financial Picture
One common mistake is negotiating property division without knowing what assets and debts actually exist. Bank accounts, retirement plans, real estate, investments, business interests, credit cards, loans, and valuable personal property may all need to be identified and valued. Financial records such as tax returns, bank statements, loan documents, and account statements can help establish that picture.
Treating the House as Automatically the Best Asset
Keeping the family home can have emotional appeal, particularly when children are involved. But ownership comes with mortgage payments, taxes, insurance, maintenance, and potentially refinancing requirements. A divorce order assigning the home to one spouse does not necessarily remove the other spouse’s responsibility for a joint mortgage.
The same principle applies to other jointly held debts. A divorce agreement can assign responsibility between spouses, but creditors generally are not bound by that agreement if both names remain on the original debt.
Overlooking Retirement Accounts and Taxes
Two assets with the same account balance may not have the same after-tax value. Retirement accounts can involve specific rules for dividing benefits, and some employer-sponsored plans require a qualified domestic relations order or another specialized process. Failing to complete the required transfer can create significant problems later.
Taxes can also affect the real value of property received in a settlement, making it important to consider more than the headline dollar amount.
Making Major Financial Moves Too Quickly
Moving money, selling property, taking on new debt, or making large purchases without understanding the legal and financial consequences can complicate a divorce. In some states, spouses also have legal obligations concerning marital property while the marriage remains intact.
Forgetting the Financial Cleanup
The work does not necessarily end when the divorce becomes final. Joint accounts may need to be separated, beneficiary designations updated, titles transferred, and passwords changed. Credit reports should also be monitored for accounts that remain connected to a former spouse.
Because property division, debt responsibility, taxation, and support rules differ by state, financial decisions during divorce should be based on the specific circumstances rather than assumptions about what happens automatically.
This post was written by a professional at the Law & Mediation Offices of Dan DeSario & Associates, a full-service law firm in Southern California specializing in family law, high-conflict divorce, child custody & visitation, domestic violence / restraining order defense, guardianships, private mediation, trials/litigation, and minor’s counsel appointments. As one of the leading law firms near you, we serve clients throughout Southern California, including Los Angeles County, Beverly Hills, West Los Angeles, San Fernando Valley (Van Nuys, Chatsworth), Ventura County, Long Beach, Redondo Beach, Manhattan Beach, Marina del Rey, Santa Barbara (existing cases), and San Diego (existing cases). If you are looking for a divorce attorney for men in Marina del Rey, CA, our experienced team provides expert guidance and reliable solutions, making us a trusted choice for family law and mediation services focused on quality, value, and performance.
